AI Property Valuation in the UK: How It Works and When to Trust It
By Rhys Hedges · Published 20 November 2026 · Last updated

An AI property valuation is an estimate of what a home is worth, produced by an automated valuation model (AVM) that compares the address with similar recent sales. It gives you a useful starting point for an offer or an asking price in seconds, but it is not a RICS valuation or a survey, and it cannot see the condition of the home. Used as one input alongside sold prices on the same road, it can help you avoid overpaying. Offer Smart is a data-led guide to what to offer, and it is built for exactly that purpose.
Key points
- An AVM is software that uses sold prices, property records and market data to value a home by comparing it with similar sales.
- It works best on standard homes with plenty of nearby sales, and it is weaker on unusual, period, extended or recently renovated properties.
- It cannot see damp, structural movement, layout or finish, so it does not replace a survey or a lender’s valuation.
- Treat the figure as a range, look at the confidence level where one is given, and test it against sold prices on the same road.
- Buyers, investors, landlords and agents can all use it to set expectations before the real negotiation starts.
Table of Contents
- What is an AI property valuation?
- What data does a UK automated valuation model use?
- How accurate is an AI house price estimate?
- How does an AVM compare with an agent’s appraisal, a survey and a mortgage valuation?
- How should you use an AI valuation when buying, selling or letting?
- What should you check when comparing AVM tools?
- How can you check what to offer on a specific home?
- What is our view on AI property valuation?
- FAQ
- Sources
What is an AI property valuation?
An AI property valuation is the output of an automated valuation model. You enter an address, the software matches it to a property record, pulls the property’s known features (type, size, number of rooms, age) and finds recent sales nearby. It then weighs those sales and adjusts them for differences such as size, type and sale date, and returns a figure, often with a range.

Not every AVM uses artificial intelligence. RICS explains in its responsible use of AI case study that some AVMs are rule-based, while many modern ones use machine learning to analyse large datasets. So when you see the phrases AI house price estimate, machine learning valuation and automated valuation model, they describe the same family of tools at different levels of sophistication.
The idea is not new, and it is not limited to private tools. The government’s guidance on model-assisted valuation explains that an AVM uses the same kind of evidence a human valuer would, namely sold prices, property characteristics and location, but applies algorithms and statistics to value many properties at a set point in time. Properties with the same characteristics are valued the same way, which makes the result consistent. The Valuation Office Agency is using this approach to support the valuation of 1.5 million homes for the 2028 Council Tax revaluation in Wales, with valuers checking the data and sampling the results.
That last point is a useful lesson in itself. Even where a public body uses a model at scale, people check the data and review the results.
What data does a UK automated valuation model use?
The quality of an estimate depends on what goes in. RICS says AVMs typically draw on comparable sales, historical transaction data, property characteristics, and geospatial and economic data, and some produce a confidence rating alongside the value.
In practice, for homes in England and Wales, that usually means:
- Sold prices: the HM Land Registry price paid records of completed sales are the backbone for most tools.
- Property attributes: Energy Performance Certificates (EPCs) often supply floor area and property type.
- Listing data: asking prices from portals such as Rightmove and Zoopla show what sellers want, which is not the same as what buyers paid.
- Area data: local trends, and sometimes transport, schools or crime.
Scotland and Northern Ireland have their own registers, so coverage and detail can differ across the UK.
Data problems are common. Paul Aylott MRICS, writing in the RICS Property Journal, points out that one building can appear as 1 High Street in one record and High Street House in another across business rates, planning and EPC data. He adds that data quality varies greatly between central government, local government and commercial providers. If a model mismatches a record, it may value your flat using the wrong floor area.
Two timing issues matter to you as a buyer:
- Sales data arrives with a lag. A completed sale reflects a price agreed months earlier, so a model can trail a market that is moving quickly up or down.
- Private and off-market sales may be missing. Anything that does not appear in the public record is invisible to the model.
How accurate is an AI house price estimate?
There is no single accuracy figure that applies to every tool or every street, and you should be wary of anyone who gives you one. What the professional guidance does say is clear on the pattern: RICS notes that AVMs are more reliable for standard, homogeneous residential property because the data is often publicly available.
In plain terms, a three-bed 1990s semi on an estate where a dozen similar houses sold in the last year is the ideal case. The model has many close comparables and few reasons to be wrong.
Estimates are less dependable when:
- the home is unusual, period, listed or rural, so there are few true comparables;
- it has been extended, converted or fully renovated, which the model may not know about;
- it is in poor condition, which the model cannot see;
- the market is small or changing fast, so older sales no longer reflect today’s prices;
- the records are wrong or out of date, for example an old EPC with the wrong floor area.
The same RICS case study warns that an AVM’s output is only as good as its training data. If the underlying data is outdated, incomplete or biased, the estimate inherits those weaknesses.
Here is a worked example of why condition matters. Imagine two identical-looking terraced houses on the same road. One has an original kitchen and old wiring. The other was fully renovated last year. A model working from public records sees two similar houses, so it may put a similar figure on both. A buyer walking round would price them very differently. This is not a flaw you can fix by choosing a cleverer tool. It is a limit of any estimate made without inspecting the property.
How does an AVM compare with an agent’s appraisal, a survey and a mortgage valuation?
These four things answer different questions, and mixing them up is where buyers get caught out.
| Type | Who it is for | What it tells you | What it does not do |
|---|---|---|---|
| AI property valuation (AVM) | You, as an early guide | A data-based estimate or range from comparable sales | Inspect the property or assess its condition |
| Estate agent appraisal | The seller | The price an agent thinks the home could achieve on the market | Provide a formal valuation |
| Mortgage valuation | The lender | Whether the property is adequate security for the loan | Tell you about defects or whether the price is fair |
| Survey by a RICS surveyor | You, as the buyer | The condition of the building and any repairs needed | Set the price you should negotiate on its own |
Lenders themselves use AVMs, which is worth knowing. Barclays says in its guide to survey and valuation services that for residential properties it will generate an automated valuation where possible, and otherwise instruct a physical valuation. It also states that the mortgage valuation is for the lender’s purposes only, is unsuitable for the buyer’s use, and that a separate survey is strongly recommended to assess condition.
For buy-to-let, Barclays’ valuation criteria explain that an AVM produces a value with a confidence level. If the confidence level is not met, the lender obtains a desktop valuation or sends a surveyor to inspect.
RICS’s position is that, for high-risk uses such as lending, legal disputes or investment decisions, AVMs should support the valuation process, not replace it. That is also why a lender can still mark a price down after you have agreed it. Our guide to a down valuation on a mortgage explains what that means and what you can do.
If the home is built in a less common way, such as timber frame, lenders can assess it differently, and it helps to understand how lenders assess timber frame homes before you rely on any estimate. A mortgage adviser can confirm what your lender will accept.
To understand the agent side, see how estate agents value properties and how you can check their numbers.
How should you use an AI valuation when buying, selling or letting?
The sensible approach is to treat the estimate as the first step in a short process, not the last.
If you are buying
- Get the estimate and note the range. A single figure suggests more precision than exists. A range and any confidence indicator tell you how much weight to put on it.
- Check the comparables yourself. Look at what similar homes on the same road and nearby streets actually sold for, and how recently. Our guide on how to find comparable sold prices shows the routine.
- Compare with the asking price. If the asking price is well above the comparable evidence, you have grounds for a lower offer. If it is below, expect competition.
- Adjust for what the model cannot see. Condition, layout, outside space, lease length and refurbishment needs all move the price. Note them on your viewing.
- Build your offer. Our step-by-step guide to calculating an offer shows how to turn the evidence into a number you can justify to an agent.
- Arrange a survey. An AVM cannot detect structural movement, damp or other defects, and these can affect value, mortgageability and repair costs. A RICS surveyor can inspect the property and tell you about them.
If you are an investor or landlord
A valuation estimate is only one line in the numbers. You also need the likely rent, running costs, mortgage payments and the area’s long-term prospects. Use the estimate to check the purchase price, then work out the yield and your return on investment. Our free property calculators cover mortgage, stamp duty and yield. For a refinance or any lending decision, expect the lender to rely on its own valuation, and for contested or high-value cases, a formal RICS valuation.
If you are selling
An estimate is a useful sense check against the figures you hear from agents. If one appraisal is far above the sold-price evidence, ask the agent which sales they used. An AVM figure can help you ask better questions, but the price you achieve depends on buyers who have seen the home.
If you are an estate agent
Buyers and tenants increasingly arrive with an estimate already in hand. Having the local evidence ready, including sold prices, schools, broadband, bills and council tax, lets you explain the gap between a model’s figure and your view of the property. We cover this below.
What should you check when comparing AVM tools?
The RICS roadmap on automated valuation models gives a practical checklist. Applied to any tool you are considering, it comes down to five questions:
- Is there a confidence score or range? The roadmap advises checking it: a low score signals unusual features or sparse market data. Confidence is usually based on the relevance, quantity and recency of the comparables.
- Can you see the comparables? A figure with no sales behind it is hard to test. Evidence you can check against the Land Registry is better.
- How recent is the data? Tools that update regularly follow the market more closely.
- How was the data collected? The roadmap also advises asking whether it is subject to selection bias.
- Has the model been benchmarked? Look for testing against actual sale prices or against qualified valuers.
RICS’s Andrew Knight also warns, in a 2022 RICS article on AVMs, that AVM outputs can be used as indicative numbers that shape consumer perceptions of value. So hold the figure loosely, however neat it looks on screen.
How can you check what to offer on a specific home?
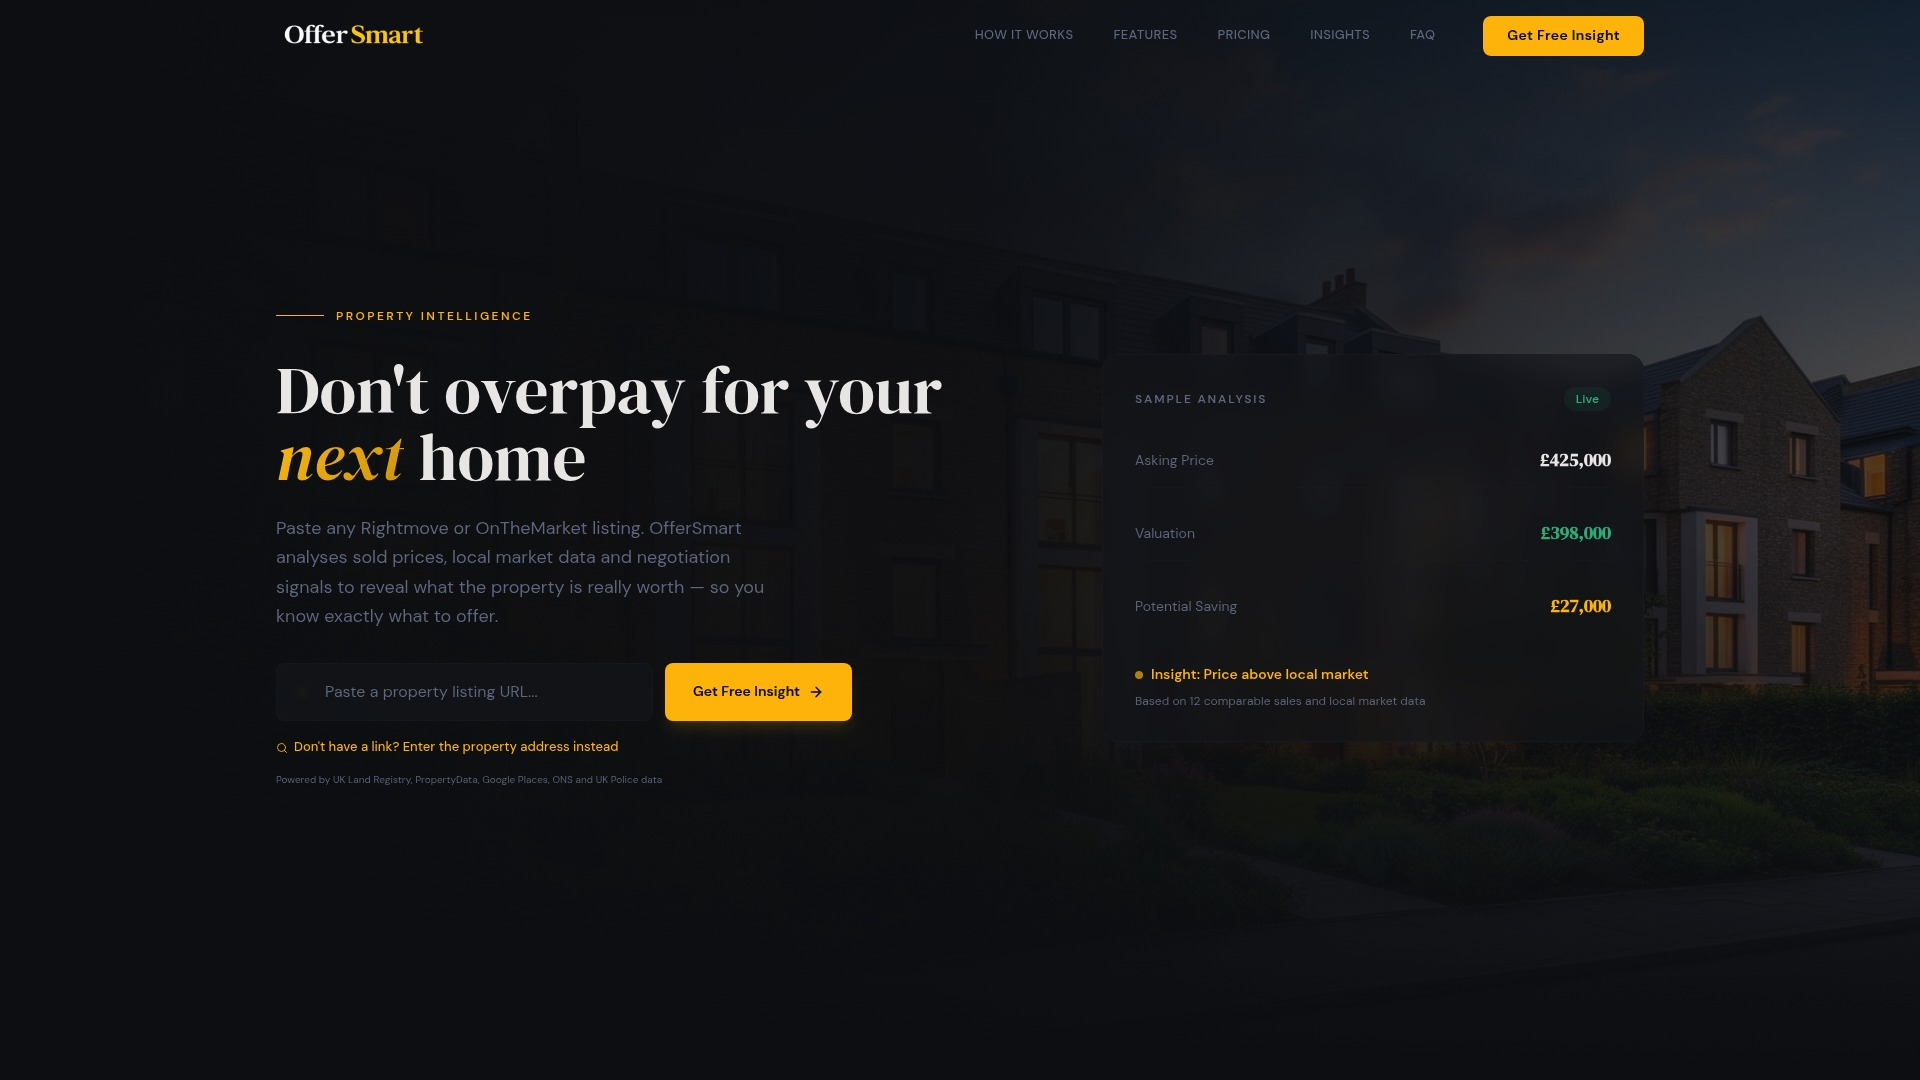
If you are about to make an offer, the most useful thing you can do is put the asking price next to the evidence. Offer Smart is a data-led guide to what to offer: enter a UK address or paste a Rightmove or OnTheMarket link, and the report compares recent local sales, including homes on the same road. It also covers crime and flood risk, nearby schools and amenities, running costs and a mortgage calculator. It is not a RICS valuation, a survey or financial advice, and it does not give an exact or guaranteed value.
The full buyer report costs £19.99 as a one-off. If you are viewing several homes, the Unlimited Homebuyer Membership is £39.99 per month. You can see what a report looks like in the sample buyer report.
Estate agents can offer the same kind of evidence to clients through branded property and area guides. The Estate Agent plans start at £49.99 per month per branch for Starter, with Growth at £69.99 and Professional at £89.99 per month per branch, and there is an example guide to look at first.
What is our view on AI property valuation?
We think an AI estimate is most useful when it is treated as evidence to be checked, not as an answer. The strength of a model is that it looks at far more sales than any person can, quickly and consistently. Its weakness is that it has never been inside the house.
That is why we focus on the evidence behind the number: recent sold prices, including those on the same road, set beside the area data that affects day-to-day life, such as flood risk, crime, schools and running costs. Our reports are a guide to what to offer, and we are clear that they are not a RICS valuation or a survey.
For buyers, we think the strongest position in a negotiation is one you can explain. An offer backed by named comparable sales is harder to dismiss than one backed by a feeling. For agents, the same evidence in a branded guide helps buyers and tenants understand a price before they ask for a discount.
Rhys Hedges
FAQ
Is an AI property valuation the same as a RICS valuation?
No. An AI valuation is a software estimate based on data about similar properties. A RICS valuation is carried out by a qualified surveyor, who can inspect the property and takes professional responsibility for the figure. For lending, legal disputes and major investment decisions, RICS says AVMs should support the valuation process rather than replace it.
Can I rely on an AI house price estimate to set my offer?
Use it as a starting point and test it against sold prices on the same road and the asking price. It cannot see condition, layout or finish, so adjust for what you saw at the viewing. A survey before exchange will tell you about defects that could change what the home is worth to you.
Why does my AI estimate differ from the estate agent’s figure?
The two use different information. A model relies on records of past sales and property data. An agent knows the local buyers, has seen the inside of the home and is pricing it to attract interest. A gap is a prompt to ask which sales each figure is based on.
Do mortgage lenders use automated valuations?
Some do. Barclays states that it will generate an automated valuation for residential properties where possible, and otherwise instructs a physical valuation. If the confidence level on a buy-to-let case is not met, it obtains a desktop valuation or inspects the property. Your lender will tell you which route applies to your application.
Sources
- RICS: Responsible use of AI case study, valuation
- GOV.UK: How model-assisted valuation delivers large-scale property valuations
- RICS Property Journal: How AI can improve automated processes in valuation
- Barclays: A guide to survey and valuation services
- Barclays: A guide to mortgage valuations
- RICS: Automated valuation models roadmap
- RICS: Automated valuation models, a property market perspective