Down Valuation on a Mortgage: What It Means and What to Do
By Rhys Hedges · Published 15 November 2026 · Last updated

A down valuation happens when the surveyor your lender appoints values the property at less than the price you agreed with the seller. The lender then bases its loan on the lower figure, so you either renegotiate, challenge the valuation with sold-price evidence, or find the difference yourself. The best protection is to check what similar homes on the same road have really sold for before you offer, which is what an Offer Smart report is built to show you, as a data-led guide to what to offer rather than a RICS valuation.
Key points
- A down valuation means the lender’s valuer puts the home’s market value below your agreed price. The lender lends against the lower figure, not the price you agreed.
- The gap lands on your deposit. On a 90% mortgage, a £50,000 shortfall in value can leave you £45,000 short.
- Your first move is usually to renegotiate with the seller. If they will not move, you can ask for a review, but only with recent, closely matched sold prices.
- Appeals are at the lender’s discretion and often fail, so build the evidence before you start, not after.
- Checking sold prices on the same road before you make an offer lowers the chance of being caught out.
Table of Contents
- What is a down valuation on a mortgage?
- Why would a lender value a home below the agreed price?
- How common are down valuations?
- How much will a down valuation cost you?
- What should you do first after a down valuation?
- Can you challenge a mortgage valuation, and when does it work?
- How do you avoid a down valuation in the first place?
- Does a down valuation matter for investors, landlords and agents?
- What does a lender’s valuation not tell you?
- Where does Offer Smart fit in?
- What do we think buyers should do before they offer?
- FAQ
- Sources
What is a down valuation on a mortgage?
When you apply for a mortgage, the lender instructs a surveyor to value the property. This is a check for the lender, so it can be sure the home is worth enough to secure the loan. It is not a survey of the building for you. If the figure comes back below the price you agreed, people call it a down valuation.
The term is informal. RICS, the professional body for surveyors, says in its Property Journal that “down-valuation” is not a technical term. It simply describes a mortgage valuation lower than the price the buyer has agreed to pay. It can mean a lower mortgage offer and can lead to a sale falling through, though it does not mean the property cannot be sold.
The key point is what the valuer is measuring. For mortgage valuations, RICS valuers use market value, defined as the estimated amount for which a property should exchange between a willing buyer and a willing seller in an arm’s-length transaction, after proper marketing. That is a different thing from the asking price, and different again from the price you agreed because you liked the house and feared losing it.

Why would a lender value a home below the agreed price?
The valuer works from evidence of what similar homes have actually sold for. RICS says market value rests on comparable evidence, usually at least three sales of similar local properties, so it may not match a seller-set asking price. SDL Surveying puts it the same way: the gap is the difference between the agreed price and market value as shown by recent transactions.
In practice, the usual causes are:
- A price that ran ahead of the sold data. A mortgage broker quoted in Which? explained that lenders do not influence what independent surveyors decide. The problem is that surveyors work from sold prices, not asking prices, so after a short, sharp rise there may be no recent sales to support higher asking prices.
- Ambitious seller pricing. Sellers sometimes set a high price or overestimate what renovation has added, as the HomeOwners Alliance guide explains.
- Condition issues the valuer notes. Damp, disrepair or Japanese knotweed can all pull a figure down. If damp is the problem, some specialists offer flexible finance for damp works, which can matter when a seller needs to put things right.
- Few comparables. New builds and unusual homes are hard to match against local sales.
- Cautious lending conditions. Farrell Heyworth lists stricter lending criteria, rapid local price growth not yet reflected in the data, surveyor caution and lower transaction volumes among the reasons down valuations have become more common.
Some of these have nothing to do with the house being a bad purchase. A fair price in a fast-moving street can still look high on paper if the last comparable sale was six months ago.
How common are down valuations?
The HomeOwners Alliance reports that down valuations affect around 5% of mortgage applications when buying, based on research carried out in April 2024, and that typical mark-downs are 2% to 5% below the agreed price. That is a snapshot and the rate moves with the market.
It rises when prices move quickly or confidence is shaky. In 2018, the BBC reported a significant rise in down valuations, with one online agent saying one in five of its sales were affected, against fewer than one in 20 two years earlier. In 2020, a survey reported by Which? found 46% of prospective buyers had seen properties down-valued since March, most by £5,000 to £10,000. Those figures describe particular periods, so treat them as a sense of scale, not a forecast.
How much will a down valuation cost you?
The lender calculates your loan as a percentage of its valuation, not your purchase price. So the shortfall is not just the gap in value: it is that gap multiplied by what you thought the lender would fund, plus the gap itself in effect, because you still owe the seller the full price.
Which? gives a clear example. You buy at £250,000 with a £25,000 deposit, so you need a £225,000 (90%) mortgage. The surveyor values the home at £200,000, and the lender offers only £180,000. You are now £45,000 short: a £50,000 drop in value became a £45,000 hole in your funding.

The HomeOwners Alliance shows the same effect at 80% loan-to-value. On a £300,000 purchase with a £60,000 deposit, you need £240,000. If the valuation is £250,000, the lender lends 80% of that, which is £200,000, leaving you £40,000 short.
The lender may also change the rate on offer. Nationwide’s guidance says that if the valuation is lower, the lender may reduce the amount it will lend or change the interest rate available, because the loan-to-value has changed. Speak to your mortgage broker or lender’s adviser about exactly how your own offer would change, since this depends on the lender’s product ranges.
What should you do first after a down valuation?
Do not panic and do not pay the shortfall by reflex. You have several routes, and the order matters.
1. Renegotiate with the seller
Which? advises that the first step is to renegotiate the price, because a down valuation is a strong bargaining tool. A written valuation from an independent surveyor, instructed by a lender, is harder for a seller to dismiss than your opinion. The HomeOwners Alliance also says the buyer’s first step should be to try to renegotiate.
What helps in the conversation:
- Ask your estate agent to pass on the valuation figure and the surveyor’s reasons, in writing.
- Propose a specific new price, not a vague request for a discount.
- Point to sold prices for similar homes nearby, not to asking prices.
- If the seller wants a quick sale, remind them a lower valuation may affect any later buyer too.
If you also have a building survey with defects in it, our guide to negotiating the price after a survey covers how to present both sets of evidence.
2. Challenge the valuation
If the seller will not move and you think the valuer got it wrong, you can ask for a review. Which? notes that a challenge needs robust evidence and that acceptance is at the lender’s discretion. Details are in the next section.
3. Cover the gap or change your borrowing
Nationwide lists the options as a larger deposit, a product with a higher loan-to-value, talking to the seller, or looking at another property or provider. Before you put in more cash, ask yourself whether you are happy paying that much more than the surveyor thinks the home is worth, because you are also tying up savings in a house that may not hold that price.
4. Try another lender
Which? also mentions trying an alternative lender that uses a different independent surveyor. A different valuer may reach a different figure, but this costs a new application and possibly new fees, and it can delay exchange. A mortgage broker can tell you whether it is realistic.
5. Walk away if the numbers no longer work
If the seller will not drop the price and you cannot or do not want to fill the gap, walking away is a legitimate result. The valuation has told you something about the market’s view of the price.
Can you challenge a mortgage valuation, and when does it work?
Yes, but the bar is high. Lenders are entitled to rely on their independent surveyors. In one Financial Ombudsman Service decision, the ombudsman found it fair and reasonable for the bank to appoint accredited surveyors and rely on their opinion, since a bank is not itself an expert in property values.
Another decision shows how appeals work in practice. One lender’s process required three comparable properties sold in the last six months, reviewed by an underwriter and then the original surveyor. The ombudsman upheld the lender because the surveyor gave reasons why the buyer’s comparables were not true matches.
What evidence a lender will look at
TSB’s published appeal form is a useful model of what lenders want. It asks for three similar properties that have exchanged or completed in the last six months, with the same property type and number of bedrooms, a similar floor area, and the same locality, ideally the same postcode. It says it will not consider estate agent marketing letters, unsold properties, or automated or indexed valuations.
RICS guidance on comparable evidence points the same way: several comparables, very similar to the property, recent, arm’s-length, and verifiable. RICS also says that where those principles were followed, a challenge is unlikely to succeed. It adds that the label “down-valuation” can prompt challenges based on little evidence.
How to build a case
- Ask your broker or lender how to request a reconsideration, and what form it needs. Farrell Heyworth says requests normally go through the broker or lender, who may consult the original surveyor.
- Collect sold prices from the last three to six months for homes close to yours in size, type and condition.
- Prefer the same road or neighbouring streets, and explain any difference, such as a newer kitchen or an extra bedroom.
- Leave out asking prices and unsold listings.
- Submit it promptly, since your mortgage offer and exchange timeline are running.
Our guide to finding comparable sold prices walks through where to look, including HM Land Registry data. Which? points to the same kind of evidence: recent sale prices of comparable homes in the same area, similar in size, condition and location, sold within the past six months.
How do you avoid a down valuation in the first place?
No one can promise a valuation figure, but you can reduce the surprise.
- Test the price against sold evidence before you offer. Asking prices are the seller’s hope. Sold prices are what the valuer will use. Our checklist on spotting an overpriced house lists seven checks you can run yourself.
- Be careful with offers above asking. In a competitive situation, it is easy to agree a price the data cannot back up. See when to offer above asking price before you stretch.
- Keep a cash buffer. If your deposit is already at the limit of what you can afford, a modest down valuation has nowhere to go.
- Be realistic about condition. Visible damp, an old roof or a short lease can affect the valuer’s figure.
- Make your offer on evidence. How much should you offer on a house explains how to build a number from comparables, and how to make an offer covers the process.
Does a down valuation matter for investors, landlords and agents?
Yes, in slightly different ways.
Investors and landlords buying with a mortgage face the same loan-to-value effect. A buy-to-let lender also looks at rental income, so a lower value can reduce what you can borrow and change the yield you are working with. Running the purchase price, expected rent and costs together before you offer shows how much headroom you have.
Estate agents see the cost of down valuations in fall-throughs and renegotiations. Agreeing a price that comparable sales support at the outset is the simplest way to keep a sale on track, and giving buyers clear local information early helps them commit with confidence.
Home movers have an extra pressure: a chain. A down valuation on the property you are buying can hold up the sale of your own home, so settle the price question quickly.
What does a lender’s valuation not tell you?
A mortgage valuation is for the lender. It confirms that the property is worth enough to secure the loan. It is not a full survey, and it will not tell you about crime, flood risk, schools, broadband or running costs. A low figure may also reflect a short run of local sales and not a fault with the home or area, which is why RICS says the term can be used loosely.
That is why a valuation should sit alongside a survey chosen for the age and condition of the property, and your own research on the area. For anything that affects your legal position or finances, speak to your conveyancing solicitor and mortgage broker.
Where does Offer Smart fit in?
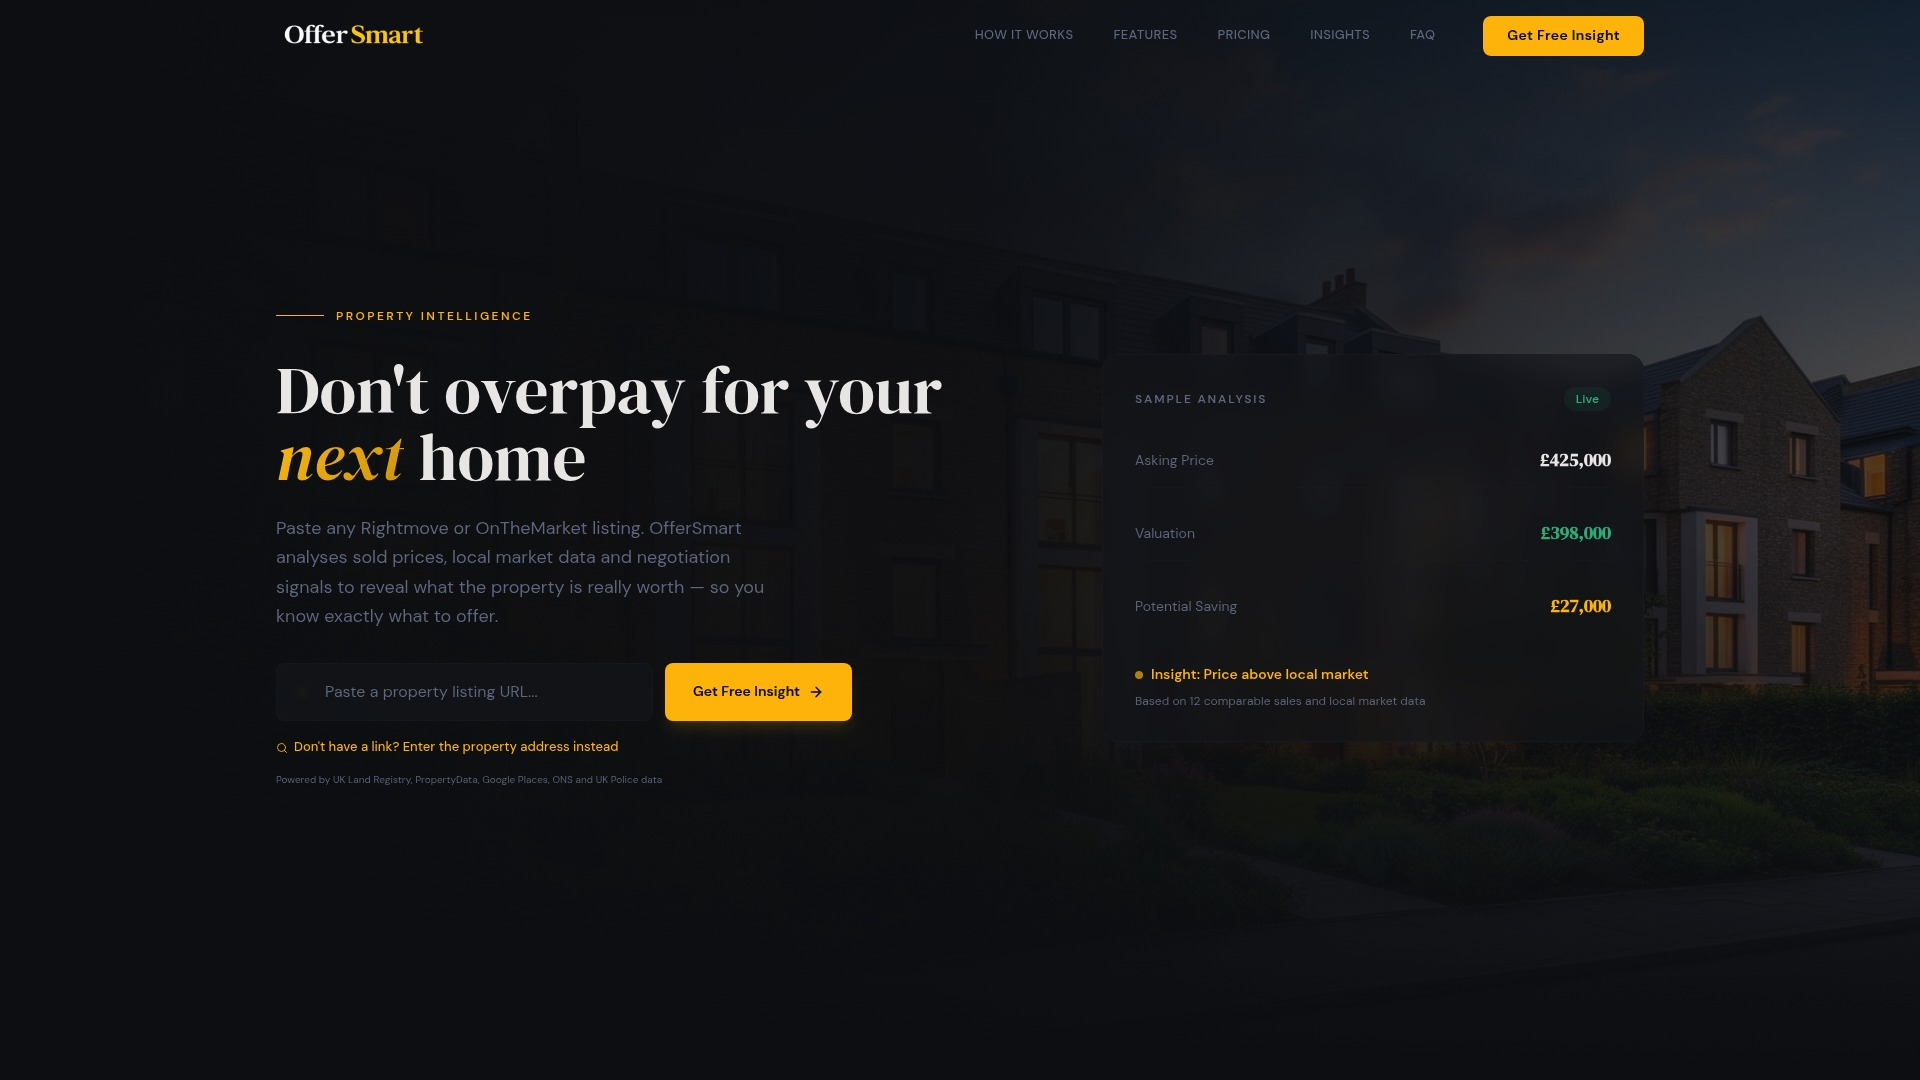
Offer Smart is a data-led guide to what to offer. It is not a RICS valuation, a survey or financial advice, and it does not give exact or guaranteed valuations. You enter an address or paste a Rightmove or Onthemarket link, and the report compares recent local sales, including properties on the same road, alongside area information such as crime risk, flood risk, nearby schools and estimated running costs.
The full buyer report costs £19.99 one-off. If you are viewing several homes, the Unlimited Homebuyer Membership is £39.99 per month. You can see what a report contains in the example buyer report first.
If you are an estate or letting agent, branded property and area guides are available on monthly plans from £49.99 per branch, covering the local information buyers ask about before they commit.
What do we think buyers should do before they offer?
Most down valuations we hear about start long before the surveyor visits. They start when a buyer agrees a price based on an asking price, a rival bid or a feeling, and not on what homes nearby have sold for.
Our view is simple. Look at completed sales on the same road and in the same street type first, then decide what you are willing to pay, and decide in advance what you would do if the valuer disagrees. A buyer who has already seen the sold prices can renegotiate calmly, challenge with proper comparables or walk away without second-guessing.
That is why we built Offer Smart around the offer decision: sold prices, area data and running costs in one report, so you go into the conversation with evidence. It is guidance to support your decision, not a substitute for the lender’s valuation, a survey or advice from your broker and solicitor.
Rhys Hedges
FAQ
What happens if a mortgage valuation is lower than the price I agreed?
The lender bases its loan on the lower valuation, so you may be offered less, or a different rate. You can renegotiate with the seller, challenge the valuation with comparable sold prices, add more deposit, try another lender or withdraw. Your broker can tell you how your particular offer changes.
Is a down valuation the same as a survey?
No. A mortgage valuation is carried out for the lender to confirm the property is adequate security for the loan. A survey is for you and looks at the condition of the building. They may be done by different people, and you should not rely on the valuation to tell you about defects.
Can the lender or surveyor be forced to change the figure?
Not as of right. Lenders can rely on their independent RICS-regulated surveyors, and the Financial Ombudsman Service has upheld that approach where the surveyor gave reasons. A review is at the lender’s discretion, so it helps to submit three or so recent, closely matched sold prices.
Should I pay the difference myself?
Only if you are comfortable paying more than a professional valuer thinks the home is worth, and you can afford the extra deposit. Try renegotiating first, because the valuation gives you a documented reason to ask for a lower price.
Sources
- “Down-valuation”: fact or fiction? RICS Property Journal
- Mortgage Valuations, SDL Surveying
- Down Valuations: 6 Options If It Happens To You, HomeOwners Alliance
- Mortgage Valuations Explained, HomeOwners Alliance
- Down valuations on the rise, Which?
- Mortgage valuations explained, Which?
- 12 reasons why mortgage lenders say no, Which?
- Rise in lenders valuing homes below sale price, BBC News
- Home Survey and Mortgage Valuations explained, Nationwide
- Financial Ombudsman Service decision DRN-4952204
- Financial Ombudsman Service decision DRN-3882934
- Low Mortgage Valuation? A Buyer’s Guide to Challenging, Farrell Heyworth
- TSB valuation and market rent appeal form
- Flexible finance for damp and mould works, Proofterior