Shared Ownership Pros and Cons: Is It Worth It?

Shared ownership can be worth it if you cannot afford to buy outright, you expect to stay for several years and you have budgeted for rent and service charges that rise over time. The main advantages are a smaller deposit and a smaller mortgage. The main drawbacks are rising costs, the cost of buying more shares and the difficulty some owners have selling. The details below apply to England, where the scheme rules are set.
Key points
- You buy a share of between 10% and 75% of the home, pay rent on the rest and need a deposit only on the share you buy.
- The monthly cost can come out below private renting, but rent and service charges both rise, and you pay 100% of the service charge.
- Staircasing (buying more shares) costs you a RICS valuation, legal fees and often an administration fee each time.
- A survey of shared owners found that 59% of respondents had struggled to sell their share.
- Rules on eviction have become stronger since 27 December 2025, but forfeiture is still possible if you break the lease.
Table of Contents
- How does shared ownership work?
- What are the advantages of shared ownership?
- What are the disadvantages and ongoing costs of shared ownership?
- Can you be kicked out of a shared ownership home?
- What is staircasing, and what does it cost?
- Is shared ownership worth it compared with renting or buying outright?
- Who is shared ownership right for?
- What do we think about shared ownership?
- Can you check the price before you reserve?
- Shared ownership questions answered
- Sources
How does shared ownership work?
You buy a share of a home, usually from a housing association, and pay rent on the share you do not own. Under the government scheme, the share you buy is between 10% and 75% of the full market value. You pay monthly rent on the remainder, plus ground rent and service charges. You can fund your share with a mortgage or savings. Every shared ownership home is leasehold, and homes are offered by housing associations, local councils and other organisations.
So, who owns the rest? Your landlord does. That is the housing association, council or other provider that sells you the lease, and it keeps the share you have not bought. You are not renting a separate property from a stranger. You hold one lease on one home, and you pay rent to the landlord for their part of it.
To apply in England, household income must be £80,000 a year or less, or £90,000 in London. You must also be unable to afford all of the deposit and mortgage payments for a home that meets your needs.
If you are buying a resale home rather than a new build, the minimum share is normally the share the seller currently owns, according to the Key Information document published in March 2026. That can be higher than the minimum on a new home, so a resale can need a bigger mortgage and deposit than you expected.
What are the advantages of shared ownership?
The benefits are mostly about getting onto the ladder with less money up front. Here are the ones that matter in practice.
A smaller deposit and a smaller mortgage
You only need a deposit on the share you are buying, not the whole price. The deposit is usually between 5% and 10% of your share. On a £300,000 home where you buy 40%, your share is £120,000, so a 10% deposit is £12,000. Buying the whole home at the same price with a 10% deposit would need £30,000.
The mortgage is also smaller, which can make it easier to meet a lender’s affordability checks. Our guide to how mortgage affordability is calculated explains what lenders look at, and it is worth reading before you apply.
A lower monthly cost than renting, in many cases
A lender’s white paper modelled a £300,000 property with a 40% share and a 10% deposit. It found a shared ownership buyer would pay £1,041 a month including mortgage, rent and service charge. That compares with £1,509 for full ownership and £1,725 for private renting. It is one model with its own assumptions, so treat it as an example, not a promise. Your own figure depends on your mortgage rate, rent and service charge.

Longer leases and some help with repairs
Under the newer model, the lease is 990 years as standard, and the minimum initial share can be as low as 10%. The landlord must also contribute up to £500 a year towards certain repairs and maintenance costs in the first 10 years. A long lease matters because short leases are harder to sell and can be costly to extend.
A route to owning more
You can buy additional shares over time. As you own more, you pay rent on less. If you can buy the whole home, you stop paying rent to the landlord altogether. Staircasing is covered in its own section below, because the costs deserve a proper look.
Wider choice than you might expect
The scheme has grown. The National Audit Office reports that annual delivery of new shared ownership homes rose from 11,128 in 2014-15 to 20,353 in 2024-25, which was 11% of all new-build supply that year. More homes generally means more choice of location and type.
What are the disadvantages and ongoing costs of shared ownership?
The drawbacks are real, and most are about costs that rise or are hard to control. Knowing them in advance lets you budget properly.
Rent on the share you do not own
For new-build homes, the rent limit is 3% of the value of the share the landlord owns, and most landlords charge 2.75%. As an illustration, on a £300,000 home with a 40% share, the landlord owns £180,000. At 2.75%, that is £4,950 a year, or £412.50 a month. Your own lease will state the actual figure.
Rent then rises each year. For leases signed before 12 October 2023, the rise can be up to RPI plus 0.5%. For leases signed on or after that date, it is either RPI plus up to 0.5% or CPI plus 1%. The National Audit Office describes the CPI plus 1% cap for post-October 2023 leases in its March 2026 investigation. Ask your solicitor which formula applies to the lease you are buying.
Service charges on 100% of the home
This is the cost buyers most often underestimate. Shared owners are leaseholders and must pay 100% of the service charges, even if they own a small share. There is no official cap, though charges are supposed to be reasonable. The landlord or managing agent sets the charge, and under the Landlord and Tenant Act 1985 it must be reasonable, as the NAO report notes. The same report says service charge increases can create affordability pressure over time.
The BBC reported a single parent in north London who bought a 25% share of a three-bedroom flat. She said her service charge had risen to more than £8,000 a year, up nearly 50% in under four years. That is one person’s account, not an average, but it shows why you should ask for several years of service charge accounts before you commit.
Our guide to ground rent, service charges and lease extensions explains how each leasehold cost works. For the wider picture of what you own and what you pay, see leasehold versus freehold.
Upfront and one-off costs
- Reservation fee: up to £500 is usually payable to the landlord. It is deducted from the amount due on completion, but if you do not complete it is usually not refunded.
- Legal fees and stamp duty: you will need a conveyancing solicitor, and stamp duty may apply. Get a quote and check the current rules with your solicitor before you reserve.
- Running costs: bills, insurance and maintenance come on top. Our house running costs guide gives a checklist to budget from.
Selling can take longer
You can sell at any time, but if you do not own 100%, you must tell your landlord. Under the new model, the landlord has a four-week nomination period to find a buyer before you can sell on the open market.
Some owners have found selling hard. A survey of Shared Owners members in February 2025 found that 83 of 140 (59%) had struggled to sell their share. The reasons included unresolved building safety issues, high service charges and a short lease that could not legally be extended. It was a survey of members of a campaign group, so it is not a random sample, but the reasons it gives are worth checking on any home you are considering.
Limited flexibility
Homes sit in specific developments, and the lease sets out what you can and cannot do. Altering the home, subletting or moving out while you keep the lease can all need landlord consent. Read the lease terms before you reserve, not after.
Can you be kicked out of a shared ownership home?
Only in limited circumstances, and the protections have improved. Your landlord may be entitled to forfeit the lease if you do not pay rent or do not keep to your lease obligations. The landlord would need a court order, and if the lease is forfeited you may lose the equity in the home and any deposit you paid.
The government is strengthening leaseholders’ rights through the Leasehold and Freehold Reform Act 2024 and increasing security of tenure for shared owners through the Renters’ Rights Act 2025, with measures introduced in phases. One industry resource explains that from 27 December 2025 shared ownership tenancies are no longer assured tenancies, so they can no longer be repossessed under Ground 8 of the Housing Act 1988 for rent arrears.
In practice, the safest approach is simple. Pay rent, mortgage and service charges on time, and speak to your landlord and lender early if you hit difficulty. If you are worried about arrears, contact a debt adviser or a housing solicitor.
What is staircasing, and what does it cost?
Staircasing means buying more shares in your home after you move in. You can usually buy shares of 10% or more at any time, though some older leases only allow 25% or more and some newer ones allow 5% or more. If you bought on or after 1 April 2021, you may also be able to buy 1% shares each year for the first 15 years.
The price of a new share depends on what your home is worth when you buy. You pay for a RICS valuation, and the landlord may charge an administration fee of around £150 to £500 each time you buy a share of 5% or more. You must buy within three months of the valuation date, or the home needs revaluing. The National Housing Federation says that under the new model you can staircase in 1% steps each year for 10 years without a valuation, with other transactions at a minimum of 5%.
Each purchase also brings legal fees, as the BBC reporting on the scheme notes. These costs are a barrier to progression, and the numbers show it. In 2024-25, 0.9% of 267,107 shared owners staircased to 100%. The government department said it was considering improvements to the model.
So if your plan is to own the whole home eventually, work out how you would pay for it. Build the valuation, legal and admin fees into the plan from day one.

Is shared ownership worth it compared with renting or buying outright?
It depends on your income, how long you will stay and how the property market moves. The evidence is mixed, and that is the honest answer.
A 2025 Leeds Building Society study, cited in the NAO’s March 2026 report, forecast shared ownership to be cheaper than private rent in 93% of areas of England over 10 years. On average, owners were £29,000 better off by year 10, and £42,000 better off in London. The NAO also records that some stakeholders consider the study optimistic about service charges, because it does not allow for them changing over time. The same report says the HomeOwners Alliance sees shared ownership as worth it if you cannot buy on the open market and plan to stay several years.
There is also a market risk. One commentator argues the scheme works financially mainly when prices are climbing, and that in a flat market buyers can be stuck for a long time. That is an opinion piece, not a forecast, but it is a fair reminder that your share can go down in value as well as up.
Here is how the three routes compare, using the lender’s £300,000 example.
| Shared ownership (40% share) | Full ownership | Private renting | |
|---|---|---|---|
| Monthly cost in the example | £1,041 | £1,509 | £1,725 |
| Deposit needed | 10% of your share | Of the full price | None, but a rental deposit applies |
| Owns the home | Part, with a lease | Yes | No |
| Main risk | Rising rent and service charges, harder resale | Higher mortgage | Rent rises, less security |
The monthly figures come from the Pepper Money white paper and use its assumptions. Treat them as a way to compare structure, not as a quote.
Who is shared ownership right for?
It suits you best if most of these are true:
- You cannot afford to buy on the open market, and you meet the income limits.
- You expect to stay for at least five years.
- Your income is stable enough to absorb rent and service charge increases.
- You have checked several years of service charge accounts and the building’s safety position.
- You have read the lease with a solicitor and understand the resale and staircasing terms.
It is a weaker fit if you may need to move within a couple of years, or if the monthly cost already uses most of your income. Before you reserve, check any home properly. Our house viewing checklist lists what to look at and what to ask the seller or landlord.
What do we think about shared ownership?
We see shared ownership as a legitimate route for buyers who would otherwise wait years for a deposit. The people who do best with it are the ones who treat it like any other purchase and look at the evidence before they commit.
Our view is that the price of the share is only part of the decision. You should know what the whole home is worth, what similar homes on the same road have sold for, and what the area is like to live in. That tells you whether the full market value used to set your share is reasonable.
Then add the running costs: rent, service charge, council tax, energy and insurance. We built Offer Smart to put comparable sales, area data and running cost estimates in one report, so you go into negotiations with comparable evidence rather than guesswork. It is a data-led guide to what to offer, not a RICS valuation, survey or financial advice, and you should still take advice from your solicitor and a mortgage adviser.
Rhys Hedges
Can you check the price before you reserve?
Shared ownership prices are tied to the full market value of the home, so it helps to see how that value compares with recent local sales. If you are looking at a resale or a similar home on the open market, our full buyer report costs £19.99 as a one-off and covers comparable sales, area data, flood and crime risk and nearby schools from a Rightmove or Onthemarket link or an address.
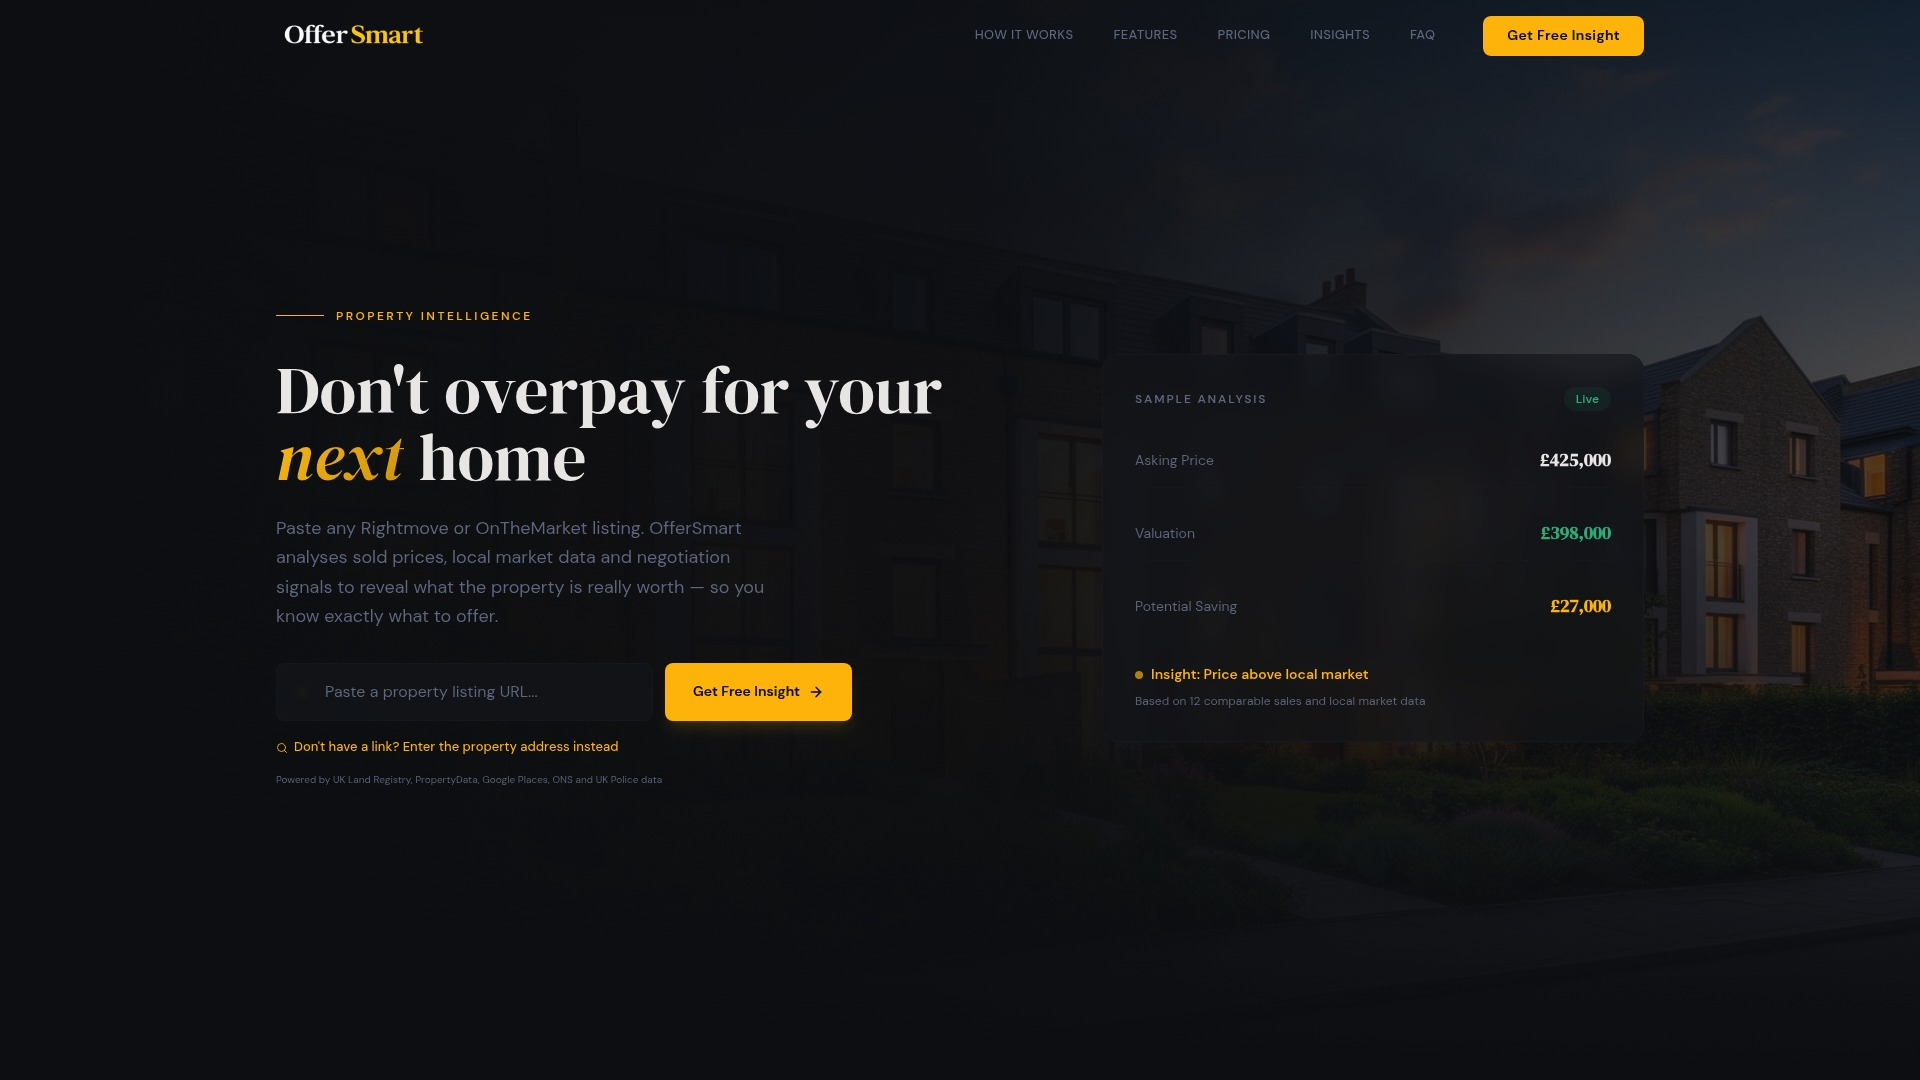
If you are comparing several homes, the Unlimited Homebuyer Membership is £39.99 per month. It is a guide to what to offer, not a valuation, and your own surveyor and solicitor remain essential.
Shared ownership questions answered
Who owns the other share of a shared ownership home?
Your landlord does, which is usually a housing association or a council. You pay rent to them on the share you have not bought. As you staircase, your share grows and the rent falls.
Can I be kicked out of a shared ownership home?
Your landlord can only forfeit the lease if you breach it, for example by not paying rent, and it needs a court order. If that happens, you could lose your equity and deposit. Protections have strengthened since 27 December 2025, but paying on time and talking to your landlord early is still the safest course.
How much deposit do I need for shared ownership?
The deposit is usually between 5% and 10% of the share you are buying. On a 40% share of a £300,000 home, 10% would be £12,000. You may also need to pay a reservation fee of up to £500, which is deducted on completion.
Can I sell a shared ownership home whenever I want?
Yes, but you must tell your landlord first if you own less than 100%. Under the new model the landlord has a four-week nomination period to find a buyer, after which you can sell on the open market. Some owners have found resale slow, so check the lease and the building’s service charge and safety position before you buy.
Sources
- Shared ownership homes: how it works (GOV.UK)
- Who can apply for shared ownership (GOV.UK)
- Shared ownership costs (GOV.UK)
- Paying rent on shared ownership (GOV.UK)
- Buying more shares, staircasing (GOV.UK)
- Key information about shared ownership, March 2026
- NAO: Investigation into shared ownership, March 2026
- NAO press release on shared ownership, 25 March 2026
- National Housing Federation: Shared ownership
- BBC: Shared ownership ‘was sold as a dream’
- BBC: ‘Wildly unaffordable’ shared ownership scheme
- Inside Housing: less than 1% staircased to 100% in 2024-25
- Shared Ownership Resources: Renters’ Rights Act
- i news: the housing schemes trapping thousands in unsellable homes
- Pepper Money: Shared ownership white paper