Housing Supply and Demand in the UK: What It Means for Buyers
By Rhys Hedges · Published 21 November 2026 · Last updated

UK house prices are set by how many people want to buy or rent against how many homes are available, and for decades the country has built too few. The ONS put the average UK house price at £273,000 in the 12 months to September 2026, up 1.2%, but that single figure hides large differences between regions and streets. The useful question for you is how supply and demand behave where you want to buy, and a data-led check of sold prices on the same road, such as the one Offer Smart produces, puts that national picture into local terms.
Key points
- The ONS recorded an average UK house price of £273,000 in the 12 months to September 2026, up 1.2%. London was the only English region with a fall, at -3.5%.
- The Centre for Policy Studies says the UK has 445 homes per 1,000 residents against 545 in the average Western European country, a shortfall of 6.9 million homes.
- Housing starts have risen, but private completions fell, so new supply is not yet catching up with demand.
- Your negotiating position depends on local conditions: sold prices nearby, how long homes sit on the market and what is being built.
- National headlines are a starting point. Your offer should rest on comparable evidence from your own street and area.
Table of Contents
- What do supply and demand mean for housing?
- How big is the UK’s housing shortfall?
- How many homes are actually being built?
- What do the latest price and rent figures show?
- Why do prices differ so much between regions?
- What factors move supply and demand?
- What does this mean for first-time buyers and home movers?
- What does it mean for investors and landlords?
- What might happen to prices next?
- How can you check local supply and demand before you offer?
- What do we think about housing supply and demand?
- FAQ
- Sources
What do supply and demand mean for housing?
Supply is the number of homes available to buy or rent. Demand is the number of households wanting one. The Urban Institute, a US research body, describes demand as driven by net household formation and supply by net new construction. That means more households forming than homes being built pushes prices and rents up. The principle is the same in the UK.
There is a second half to it. Research published by the NBER argues that high prices need both strong demand and limited supply. If demand is weak, prices cannot stay high however few homes there are. If building is unrestricted, prices cannot climb far above the cost of producing a home. The places with the highest prices tend to be those where building is hardest to get approved.
The LSE adds the point that matters most for UK buyers: where supply is inelastic, meaning it cannot respond quickly, extra demand shows up as faster price rises rather than new homes. This is most likely in dense towns and cities where planners protect historic buildings or open space. It names Bristol, London and Manchester as places where prices rose fastest over the past decade.
How big is the UK’s housing shortfall?
The Centre for Policy Studies (CPS), a think tank, calculates in its October 2026 report that the UK is 6.9 million homes short of the Western European average, or 6.2 million in England alone. The UK has 445 homes per 1,000 residents. The average Western European country has 545. London is lowest of any UK region at 422 per 1,000.

The same report says England has built only 178,000 homes in the average year since 1982, just over half the government’s 300,000-a-year target. That target is the annual rate needed to reach 1.5 million homes in this Parliament.
Public opinion matches the numbers. Ipsos’s 2025 Public Services survey of 20,000 UK adults found 59% dissatisfied with local housing affordability and only 12% satisfied. Seven in ten think there is a housing crisis.
How many homes are actually being built?
The House of Lords Library notes that around 199,500 net additional homes were delivered in England in 2025/26. That is below the yearly level needed to hit the 1.5 million target, although housing starts have recently increased and affordable housing delivery is rising.
The Chartered Institute of Housing reported in October 2026 that the UK Housing Review expects only around one million homes by July 2029, about 500,000 short. It points to energy-efficiency and Decent Homes Standard costs for social landlords, and construction costs and viability for private developers.
The mix of homes matters as well. RSM UK’s Q2 2026 housing tracker found housing starts up 14% year on year, yet private residential completions down 21% to just over 28,000. Housing association and local authority completions rose 12%. RSM reads the gap as a sign that planning issues and build costs, not only weak demand, are holding back private supply.
For a buyer, this means a new-build pipeline that is less reliable than the headlines suggest. If you are waiting for more homes to come to market in your area, check what has actually been completed and what has only been started. Our guide to checking planning applications on any UK property shows how to see what is proposed near a home you are considering.

What do the latest price and rent figures show?
The ONS bulletin for November 2026 gives the clearest snapshot of how supply and demand are balancing out. These figures apply to the periods shown and are updated monthly, so check the live release for the latest.
| Area | Average house price (12 months to September 2026) | Annual change |
|---|---|---|
| UK | £273,000 | +1.2% |
| England | £293,000 | +0.8% |
| Wales | £215,000 | +1.8% |
| Scotland | £198,000 | +2.3% |
London was the only English region with negative annual house price inflation at -3.5%, and Inner London fell 7.2%, its largest annual fall since August 2009, according to the ONS. The House of Commons Library records that, excluding Northern Ireland, prices grew fastest in the North East and Wales between August 2025 and August 2026, while falling in London and the South East.
Rents tell a different story. The same ONS bulletin reports average UK private rent up 3.8% to £1,411 in the 12 months to October 2026. England averaged £1,472 (+4.0%), Wales £849 (+3.9%) and Scotland £1,015 (+0.7%). Within England, rent inflation was highest in the North West at 5.6% and lowest in the South West at 3.3%.
So prices are almost flat nationally while rents keep rising faster. That points to continued pressure on renters and a steady supply of would-be buyers who cannot yet afford to purchase.
Why do prices differ so much between regions?
Because supply and demand are local. The ONS affordability bulletin shows the spread for 2025:
- The median home in England cost £300,000, or 7.6 times median full-time earnings of £39,300.
- In Wales the average home cost £213,000, or 6.0 times median earnings of £35,800.
- The North East’s average home cost 5.0 times earnings, while London’s cost 10.6 times.
- Hyndburn and Kingston upon Hull were the most affordable local authorities (ratio 4.1). Kensington and Chelsea was the least affordable (25.2).
The ONS also notes that affordability has improved since the 2021 peak, with prices up 5% but earnings up 25% since then.
Why such a wide gap? In a high-demand area with little land and strict planning, extra buyers push up prices because few new homes can be added. In a lower-demand area with more space, supply can respond more easily. Two streets a mile apart can have different conditions again, depending on school catchments, transport links and the type of stock.
What factors move supply and demand?
The LSE lists the main forces behind each side of the market.
Demand
- Mortgage rates and the amount lenders will lend
- Population growth and household formation
- Real incomes
- Demand for space
- Social norms and government policy
The LSE puts the share of the UK population preferring owner-occupation at 86%.
Supply
- Land availability
- Profitability for developers
- Regulation and planning
- Construction material costs
- Labour shortages
- Local opposition to new development
LSE economists Christian Hilber and Andreas Mense, cited by the House of Lords Library, argue that structural obstacles to building, rather than temporary financial conditions, are at the heart of the UK’s long-term affordability challenge. Prices grow most where supply is most tightly constrained. A guide to housing supply constraints explains how these limits work in more detail.
Mortgage affordability is the demand-side lever buyers feel most directly. Our explainer on how mortgage affordability is calculated in the UK sets out how lenders decide what you can borrow.
What does this mean for first-time buyers and home movers?
The Lords Library reports that 65% of English households owned their home in 2024/25, below the 71% peak in 2003. The average first-time buyer age rose from 31.4 in 2003/04 to 33.9 in 2024/25. England’s price-to-earnings ratio was 7.63 in 2025, against roughly four in 2000.
Those are national averages. In practice, three things matter to you:
- Your region sets your leverage. Where prices are falling or flat, as in London and the South East in the ONS figures, sellers often have less room to hold out. Where prices are rising fastest, such as the North East and Wales, expect less room to negotiate.
- The asking price is a seller’s opinion. The price a comparable home sold for is the evidence. HM Land Registry publishes sold prices, and the most useful ones are for the same road and similar property type in the last year or so.
- Your ceiling is a budget, not a market price. Work out your maximum with your mortgage broker, add stamp duty and conveyancing costs, and decide before viewing what you will not go beyond.
If you are deciding what to bid, our guide on how much to offer on a house walks through the comparables, and how to tell if a house is overpriced lists seven checks to run before you commit.
What does it mean for investors and landlords?
Tight supply supports rents, and the ONS rent figures above show it. The question for an investor is whether a particular home delivers a return after costs, not whether the national picture is favourable.
Regional differences are the place to start. The North West recorded the highest English rent inflation (5.6%), while the ONS regional price data shows lower entry prices in the North East, Wales and Scotland. Yield depends on both the price you pay and the rent you achieve, so the two figures must be looked at together. Our rental yield calculator shows the gross return on any purchase price and monthly rent.
Two supply-side points are worth checking on any buy-to-let:
- New rental supply nearby. RSM notes that higher-density Build-to-Rent schemes have been hit hardest by the build-cost squeeze, which affects how much new rental stock reaches some towns.
- Planning and permitted development. What can be added to a property can change its value and its rent. Our guide to permitted development rules explains what you can build without planning permission.
What might happen to prices next?
Forecasts are opinions, not data, and they move with interest rates. RSM UK forecasts that house prices will stagnate during 2026, with falls of 2 to 3% in the South East and London, then grow 17 to 20% over the four years to 2030. It expects mortgage reform to boost borrowing capacity and support demand.
The supply evidence points the same way. If the CIH is right that England will deliver around one million homes by July 2029, the shortfall against the 1.5 million target stays in place and continues to support prices over the longer term. In the short term, local conditions will count for more than any national forecast. Our piece on the 2026 UK house price forecast compares what different experts expect.
How can you check local supply and demand before you offer?
Start with what is on the market and what has sold. A street with several similar homes for sale and slow sales gives you leverage. A street with one listing and quick sales does not.
Our Full buyer report costs £19.99 as a one-off. You enter an address or paste a Rightmove or OnTheMarket link, and it compares recent local sales, including homes on the same road, alongside area data on crime and flood risk, nearby schools and running costs. If you are viewing several homes, the Unlimited Homebuyer Membership is £39.99 per month. It is a data-led guide to what to offer, not a RICS valuation, a survey or financial advice.
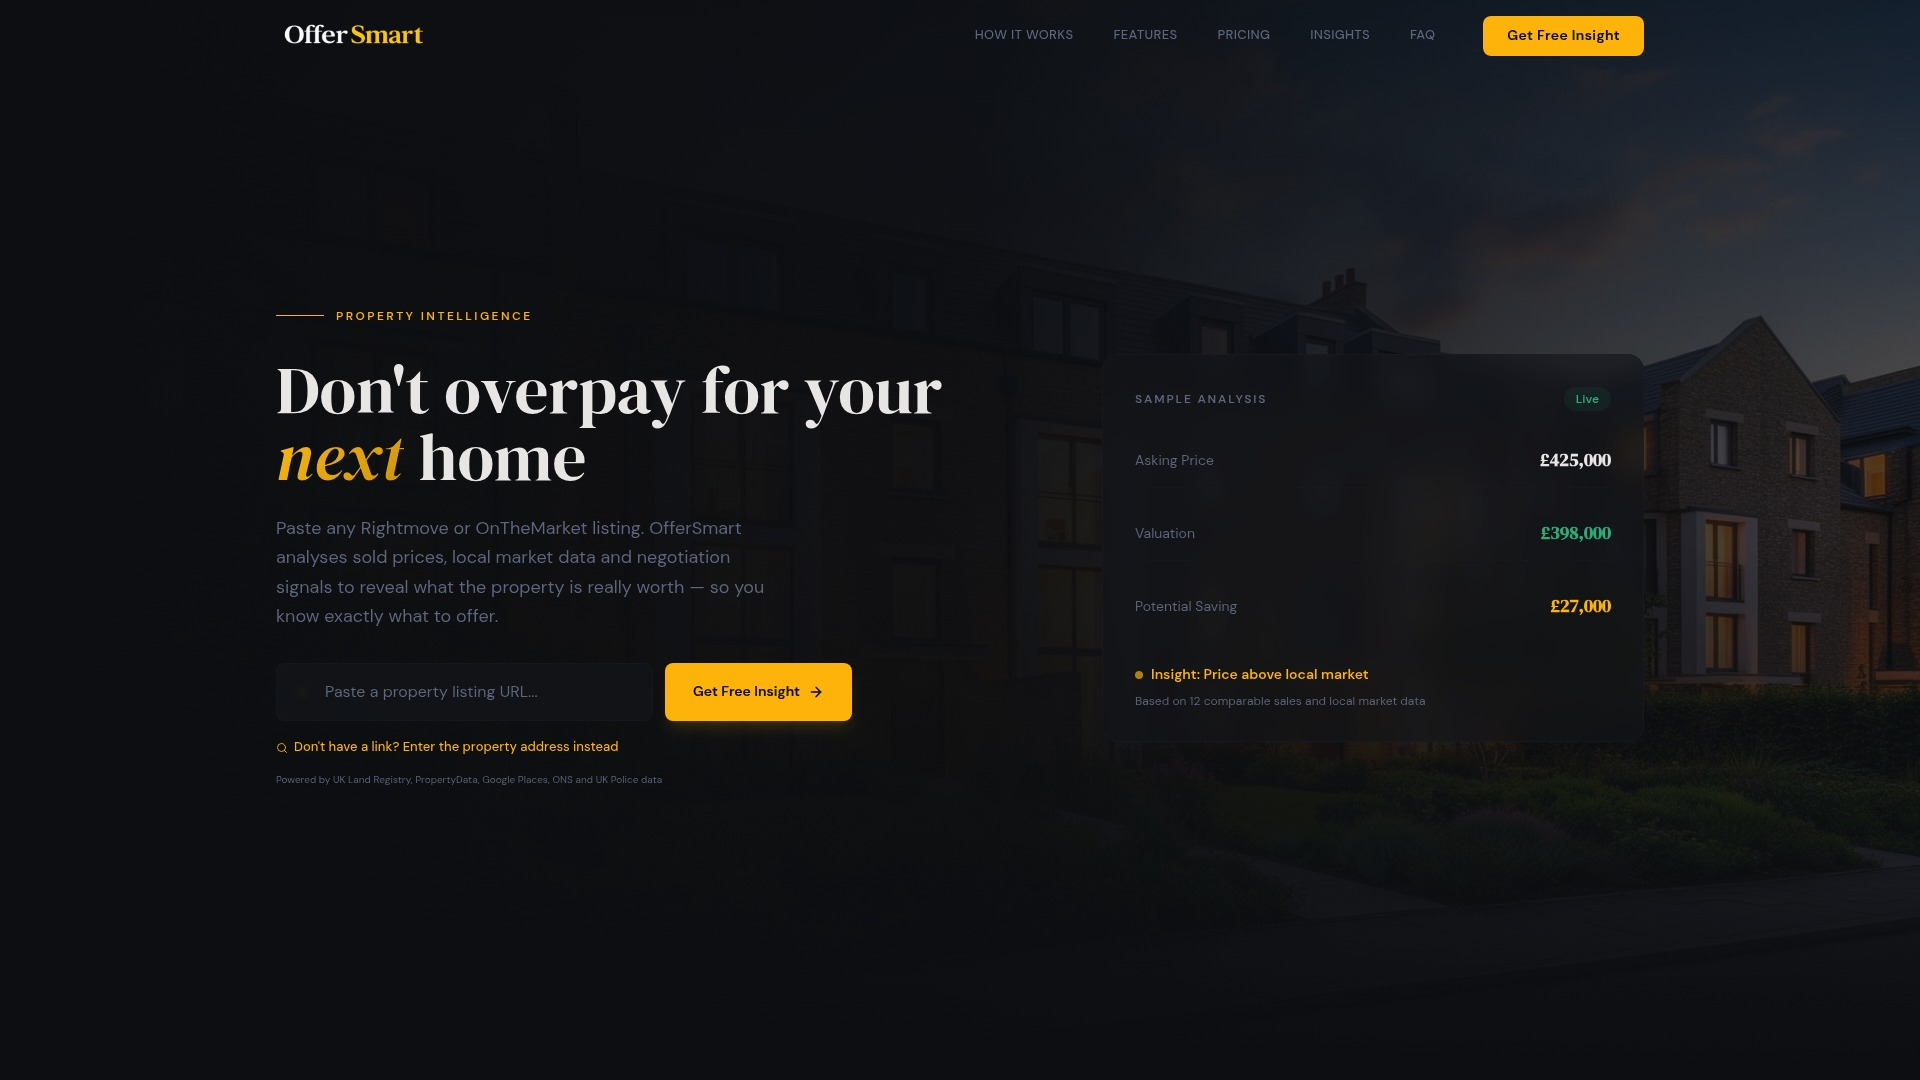
Agents can use the same data in branded property and area guides for buyers and tenants, on the estate agent plans from £49.99 per month per branch.
What do we think about housing supply and demand?
We read the national numbers the way a buyer should: as context, never as the price of the house in front of you. A shortage of 6.9 million homes is real, but it does not tell you whether the three-bedroom semi you are viewing is worth the asking price.
Supply and demand play out street by street. Two homes in the same postcode can sit in very different conditions, and the best evidence of that is what similar homes nearby have actually sold for. That is why our reports start with recent local sales, including the same road, and then add the area data that shapes how the home will live: schools, flood and crime risk, running costs and council tax.
We built Offer Smart for three kinds of reader. Buyers want to avoid overpaying. Investors want rental value and return set against the price. Agents want to hand clients a clear guide to the area. In each case the aim is the same: replace guesswork with evidence before one of the largest financial commitments you will make.
Rhys Hedges
FAQ
Is there a housing crisis in the UK?
The evidence says yes. The Centre for Policy Studies puts the UK 6.9 million homes short of the Western European average, and Ipsos found seven in ten Britons believe there is a housing crisis. The ONS shows home prices at 7.6 times median earnings in England in 2025, although this has improved since the 2021 peak.
Are UK house prices rising or falling?
The ONS reported a 1.2% rise in average UK prices to £273,000 in the 12 months to September 2026, with London down 3.5%. The picture changes each month, so check the latest ONS release and local sold prices for your area rather than relying on one headline.
Why does low housing supply push prices up?
When more households want homes than there are homes available, buyers compete and sellers can hold out for higher prices. The LSE explains that where new building cannot respond quickly, extra demand shows up as price rises rather than new homes.
Does the national shortage give me more power to negotiate?
Not directly. National shortage does not decide your deal. Local evidence does: how many similar homes are listed, how long they take to sell and what they achieved against their asking prices. Use sold prices from your own road and area to set your offer.
Sources
- Private rent and house prices, UK: November 2026, ONS
- Housing affordability in England and Wales: 2025, ONS
- Housing market: Economic indicators, House of Commons Library
- Home ownership in England, House of Lords Library
- The UK’s Housing Crisis is Getting Worse, Centre for Policy Studies
- Housing, Public Services 2025, Ipsos
- UK housing tracker outlook, Q2 2026, RSM UK
- Government on course to miss 1.5 million homes target, Chartered Institute of Housing
- How does supply and demand affect the housing market? LSE
- Place the Blame Where It Belongs, Urban Institute
- The Supply Side of Housing Markets, NBER